Could a simple drainage fix keep you from paying tens of thousands after you spot a crack? Or will insurance cover foundation repair?
I’m the owner of Drainage First, a local Metro Atlanta drainage and grading company with 20+ years on the ground. I see one truth over and over: most home damage starts outside. Call us at (678) 389-9544 or email carter@drainagefirst.com to discuss solutions for your Atlanta property and stop flooding before it starts.
Home policies often pay for sudden, accidental events, not slow wear. That distinction decides whether a claim is accepted more than the sticker shock of a costly job. Average fixes sit between $2,188 and $7,884, but severe cases can reach $100,000.
We focus on practical, exterior solutions—grading, gutters, and spot drainage that prevent basement water and cut the chance of interior work. This guide explains what typically gets paid, what does not, and how to read your policy before you call a contractor.
Key Takeaways
- Coverage usually depends on the cause of the damage, not repair price.
- Drainage fixes often prevent bigger home problems later.
- I’ll show how to read policy language to make smarter choices.
- Average costs vary; prevention can save thousands.
- Drainage First offers practical exterior solutions in Metro Atlanta.
Why foundation repair coverage depends on the cause of the damage
What broke your wall matters—more than how much it costs to fix it. Your home foundation supports the whole house, so insurers treat problems as high-stakes events that need a clear cause. A policy lists perils that trigger payouts and lists exclusions that don’t.
What your foundation does and why insurers treat it differently
The slab or stem wall holds floors, walls, and load points. When that system fails, the claim shifts from a small fix to a structural one. Insurers want proof of a covered cause before agreeing to pay.
The “sudden and accidental” standard vs. gradual deterioration
The basic rule: sudden, accidental events may get paid. Slow settling, long-term seepage, and soil movement usually do not. Repeated wet/dry cycles or shifting clay can create dramatic damage that a policy calls maintenance.
- Document timing: photos and dates show what happened and when.
- Know perils: your policy is a list of causes, not a blank check.
- Preventive step: improved grading and drainage often stop damage caused by soil and moisture.
Will insurance cover foundation repair under a standard homeowners policy?
Insurers usually pay when a sudden event clearly harms a home; the key is proving the timing and cause.
Covered perils that often trigger structural payouts
A standard policy treats the structure as part of the home, so damage from listed perils can extend to base work.
- Fire and smoke
- Wind and hail
- Explosions and vandalism
- Impact events like a vehicle strike or a falling tree
Examples insurers commonly accept
Common, accepted scenarios include a car hitting a wall or a storm-toppled tree cracking a load-bearing section.
When water losses may qualify
Sudden events, such as a burst pipe, often trigger coverage for related water damage.
But slow groundwater seepage, chronic damp, or long-term soil movement is usually excluded.
Practical steps: document dates, photos, and emergency repairs. Call a contractor for a quick diagnostic if cause is unclear. Then decide if a claim to your insurance company makes sense given your deductible and claim history.
Foundation damage that home insurance usually won’t cover
Not every crack or wet basement is something your home policy pays for. Many exclusions are common and clear. I list the big ones so you stop guessing and start preventing problems.
Flooding and separate flood policies
Flood losses are generally handled by a separate flood policy. Even a flooded basement from heavy rain often needs that extra plan.
Earth movement and ground shifts
Events like earthquakes, sinkholes, mudslides, and other soil movement usually fall outside standard home policies. When the ground itself shifts, claims are often denied.
Wear, neglect, and settling
Slow wear, normal settling, and deferred maintenance are not covered. Small cracks and sticking doors due to gradual soil change are treated as homeowner upkeep.
Poor construction and pests
Faulty construction or workmanship is commonly excluded. Insurers expect builders or warranties to handle those problems. Pests and root damage also sit outside most policies.
- Plain fact: floods, ground movement, wear, bad construction, pests—these are often excluded.
- Prevent foundation issues by controlling runoff and keeping soil moisture steady.
- Practical step: improve grading and exterior drainage to avoid problems that leave you paying out of pocket.
How to tell what your insurance policy covers for foundation issues
Open your policy packet and find the declarations page; it gives the headline limits and endorsements.
Then go to the exclusions section and any endorsements that change standard wording. If you don’t have a copy, request the full home insurance policy from your insurance company before you file a claim.
Where to look in the paperwork
- Declarations page: limits, deductibles, listed perils.
- Exclusions: what the policy specifically omits.
- Endorsements: additions or deletions that change what may cover damage.
Questions to ask your agent or company before filing
- Does this policy itemize the cause that may cover the damage?
- How do deductibles and coverage limits affect a structural claim?
- What is the claim reporting window and the adjuster process?
- Does the company treat different water type claims differently (burst pipe vs. seepage vs. backup)?
- Should I document maintenance to show lack of neglect?
Practical step: clarify unclear wording with your agent, gather photos and dates, then call us at Drainage First if the issue looks drainage-related. That saves time and helps you decide whether a claim makes sense.
Other coverages that may help with foundation repairs
Some homeowners expand protection with targeted policies and endorsements. I recommend checking these options if you live in a flood-prone area or have an older sewer line.
Flood insurance basics and basement limits
Flood policies are separate from your home policy. They often limit payments for basements to certain structural parts, not finished rooms or personal property.
Read the policy language. Know what structural elements are included and what is excluded. That avoids surprises after a major rain event.
Earthquake coverage and cracked concrete
Quake policies commonly pay to fix cracked concrete and make structural repairs tied to seismic events.
They rarely pay to re-stabilize or re-fill shifted ground under the slab. That kind of work often falls to the homeowner or a specialist warranty.
Water-backup endorsements for sewers and sumps
A water-backup endorsement is an add-on that responds to sewer, drain, or sump pump failures. It helps when water comes from a blocked line, not from surface flooding.
If you have recurring basement moisture or finished spaces below grade, this endorsement is a cost-effective option to consider.
- Match risk to coverage: flood policies for flood-prone lots; quake for seismic zones; water-backup for older plumbing or sump systems.
- Most cost-effective step: reduce water pressure at the wall with exterior grading and improved drainage before buying extra policies.
- Claims strategy: know your add-ons so you act calmly after damage and avoid unnecessary expenses.
How to file a foundation repair claim and avoid common delays
Start a claim by getting clear proof: dated photos, short video, and a simple written timeline. That record sets the pace and reduces back-and-forth with the company and adjuster.
Document the damage with photos, videos, and timelines
Take wide shots to show context and close shots to show the crack or water line. Record short video walkthroughs narrating dates and conditions.
Keep a one-page timeline. Note when you first saw the damage, weather events, and any temporary fixes.
Protect the property with critical repairs and keep receipts
Make emergency repairs that stop more damage. Save every receipt and invoice. Those documents support reimbursement for necessary repairs.
Working with the claims adjuster and contractor estimates
Call your insurance company to report the claim and schedule an adjuster. Be present during inspections and share contractor notes.
Get at least two estimates that address the root cause, not just cosmetic work. Email all estimates to the adjuster and keep written records of conversations.
Understanding deductibles, payouts, and mortgage company involvement
Know your deductible and how it affects payouts. Mortgage companies sometimes hold funds and require extra paperwork, which can add time.
Practical checklist:
- Photos, video, timeline dated
- Emergency fixes saved with receipts
- Multiple contractor estimates
- Adjuster attendance and written communication
Foundation warning signs homeowners should not ignore
When floors tilt or doors stick, that’s your house telling you something has changed below grade. Catching signs early usually costs far less than fixing major damage later.
Watch for these common problems after heavy rains or long dry spells in the Atlanta area.
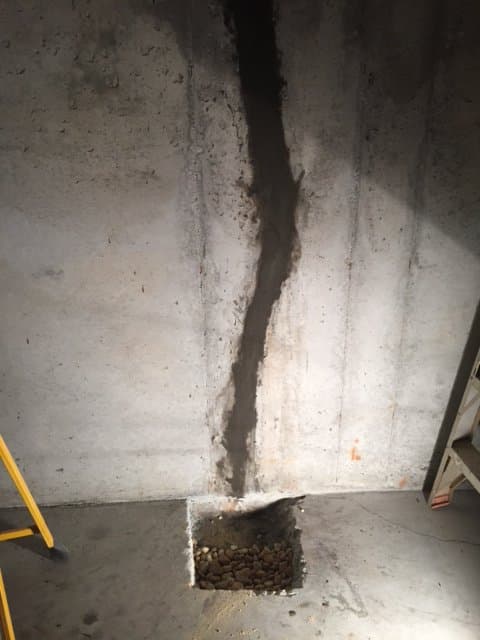
- Cracks: Vertical or horizontal cracks in basement walls or slabs, and stair-step cracks in brickwork, can signal movement.
- Sticking doors and windows: Frames that bind or won’t latch point to shifting that affects the whole home.
- Sloping floors: Uneven or sagging floors suggest the structure is settling unevenly.
When to bring in a professional evaluation
If you see sudden changes, rapid crack growth, water intrusion, or two or more symptoms together, call for an assessment. A short diagnostic is usually far cheaper than large-scale fixes and helps document timing if you later discuss claims.
Practical step: take dated photos over weeks to track progress. In many cases, improving grading and controlling water near the wall is the practical move to prevent foundation damage and stop soil-driven issues from getting worse.
Prevent foundation damage with smarter drainage and grading
Controlling runoff around the perimeter often prevents slow movement that leads to costly fixes. Start with simple, low-disruption steps that stop saturation near walls and reduce foundation damage risk over time.
Control roof runoff: gutters, downspouts, and directing water away from the home
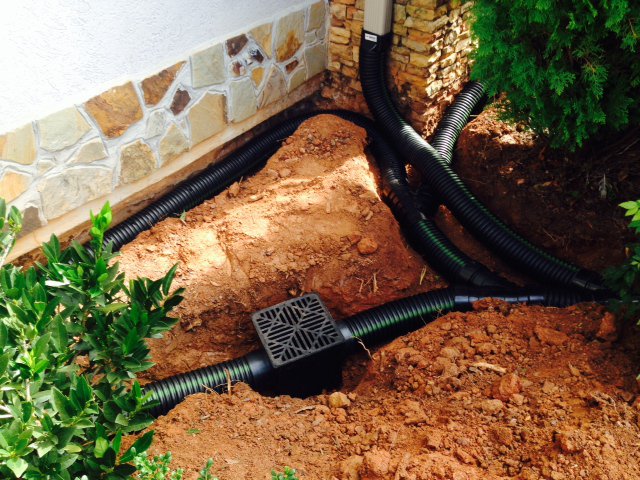
Keep gutters clean and extend downspouts several feet away from the house. Use splash blocks or extensions so water drains beyond the immediate footing.
Improve exterior drainage: grading, French drains, and keeping water from pooling
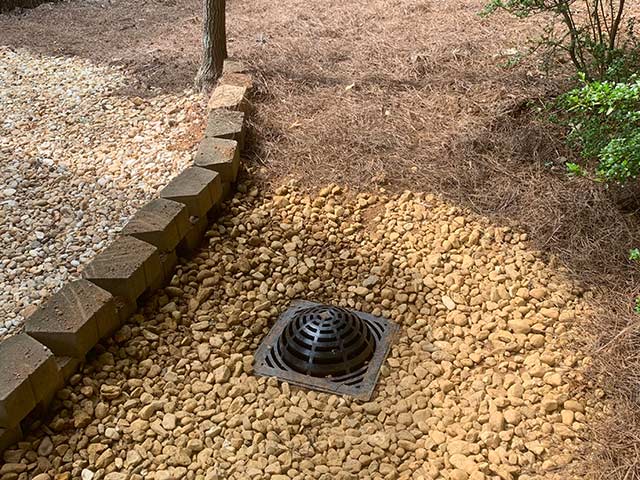
Grade soil to slope away from walls and install French drains where pooling occurs. These options relieve hydrostatic pressure and limit the need for costly interior systems.
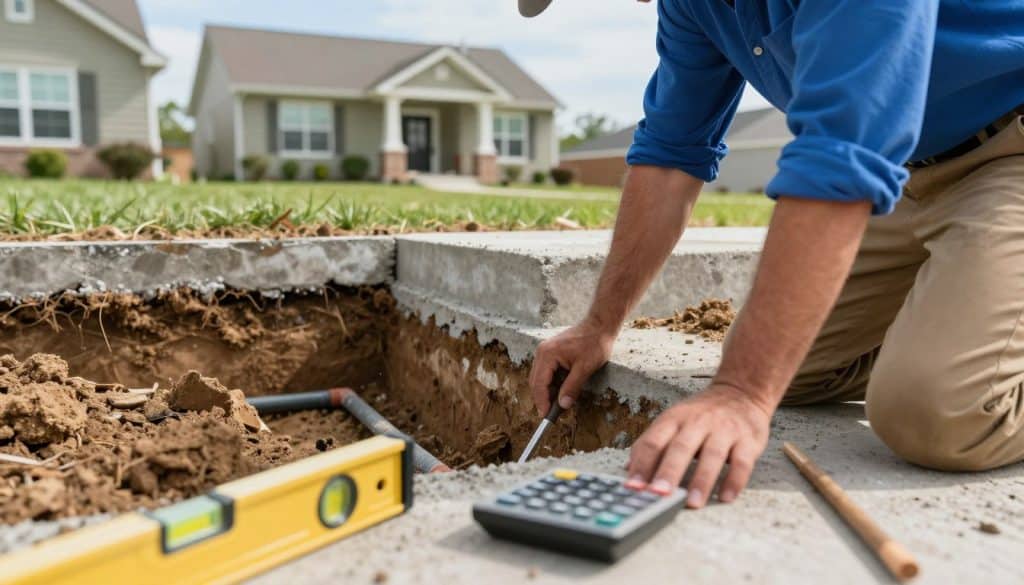
Manage soil moisture to reduce expansion, contraction, and shifting
Maintain even moisture around the yard in dry spells and after heavy rain. In Georgia, swings between wet and dry make soil move more and raise the chance of structural issues.
Landscaping choices that can cause damage: trees, roots, and planting distance
Avoid planting large trees near the footing. Roots can draw moisture or disturb soil, creating movement that leads to costly repair work.
Why prevention often costs less than major repairs:
- Exterior fixes are usually quicker and cheaper than structural restorations.
- Addressing runoff and grading reduces the chance of damage caused over years—which many home insurance policies exclude.
- At Drainage First, I lead calls, provide a same-day written estimate, and focus on exterior solutions first to save time and avoid disruptive interior systems.
Conclusion
The key question is not cost, but what triggered the damage and when it began.
Coverage depends on cause, timing, and clear proof in your policy and claim file. Document photos, dates, and any sudden events. Read your paperwork before you call for quotes.
For most Metro Atlanta homes, smart grading and targeted drainage stop slow soil movement and reduce future harm. Treat exterior steps as protection for the structure, not an optional upgrade.
I run Drainage First, a locally owned company with 20+ years on the ground. I handle calls, give a same-day written estimate, and start quickly when needed. Call (678) 389-9544 or email carter@drainagefirst.com for a straightforward evaluation in Metro Atlanta and nearby areas.